
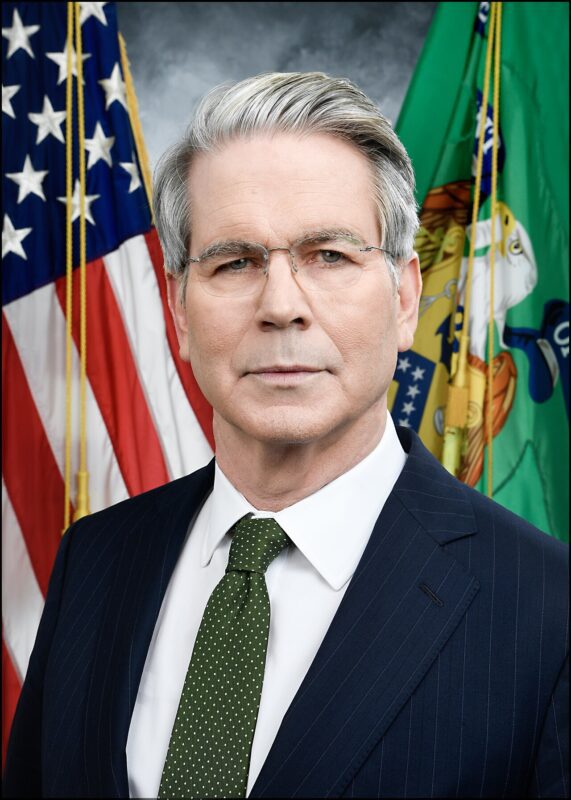
Treasury Secretary Scott Bessent walked back his “I am the house” declaration in a televised interview with Axios after bond yields continued rising, according to MarketWatch. He also defended his department’s bond-market record, putting a more qualified public response behind a boast he made a month earlier.
The shift is the central development in MarketWatch’s account: Bessent had projected confidence about his position in the market, but the subsequent rise in yields gave him reason to revisit that language. The supplied report does not reproduce his new explanation verbatim, so it does not establish precisely how he qualified the original statement.
That distinction matters. MarketWatch describes both a walkback and a defense of the Treasury’s performance, not an abandonment of the department’s approach. Bessent’s latest appearance therefore leaves two separate questions for readers: what he now means by his earlier declaration, and whether the results support his defense of Treasury’s record.
A boast meets a market test
The timeline provided by MarketWatch is straightforward. Bessent made the “I am the house” declaration a month before the Axios interview. Bond yields did not stop rising. In the later televised appearance, he addressed the department’s performance and stepped back from the earlier wording.
MarketWatch’s headline explicitly connects the interview to that continued increase in yields. It does not, however, establish that the remark caused the increase. The difference between a market moving after an official speaks and moving because of that statement is essential to judging this episode fairly.
The available excerpt supplies no starting or ending yield, no change measured in basis points and no specific Treasury maturity. It consequently does not support a numerical assessment of how much conditions deteriorated during the month, or which part of the bond market experienced the greatest pressure.
What it does document is a gap between Bessent’s confident language and the direction of the market. His defense in the Axios interview is significant because it addresses that gap without, in the supplied account, conceding that his department’s broader record warrants the criticism.
Scrutiny extends beyond the remark
Related headlines included in the source material show that scrutiny has extended to Treasury’s actions as well as its messaging. An NBC News headline characterized Bessent’s move to tamp down rising rates as backfiring, with bond yields jumping and stocks tumbling. That is the outlet’s characterization; the accompanying article and its supporting figures were not included.
A Fortune headline similarly framed Bessent’s bond plan as showing markets what would make Treasury “flinch.” Another Fortune headline contrasted his “I am the house now” statement with a bond market that “didn’t listen.” Together, those headlines illustrate the critical reception surrounding his assertion of strength, rather than provide a detailed account of the policy’s mechanics.
Other coverage pointed toward those mechanics. A Council on Foreign Relations headline focused on a Treasury “buyback surprise,” while CNBC described Bessent as moving to curb Treasury yields. The supplied material does not identify the terms, scale or schedule of those actions, making it impossible to assess their design from this record alone.
There is also a relevant difference in framing among the reports. A Financial Times headline tied the “I am the house now” language to a warning that currency traders should not bet against the yen. That context cautions against treating every appearance of the quotation as an identical, narrowly defined promise about Treasury yields.
What readers can watch next
For readers assessing Washington’s management of the bond market, the immediate takeaway is narrower than either a victory claim or a sweeping verdict of failure. MarketWatch reports that yields kept rising and Bessent moderated his language. Its supplied excerpt does not quantify the outcome or provide his full rebuttal.
Nor does it announce a next policy step, a timetable for additional action or a yield target against which the department should be judged. Those details would be necessary to turn this public dispute over credibility into a concrete assessment of Treasury’s plans and results.
The next meaningful test is therefore the substance behind the defense: the department’s explanation of its actions, the evidence supporting its claimed record and the market’s subsequent direction. For now, MarketWatch’s account establishes a change in Bessent’s rhetoric, while leaving the larger policy argument unresolved.
Source: marketwatch.com

Leave a comment